1. A Different Question
A common question is what a longer tenure does to the EMI on a loan you have already chosen: the EMI falls and the total interest rises. This article asks something else. If the monthly EMI you can carry stays the same, what does a longer tenure do to the size of the loan?
The answer matters when the EMI is the thing you are holding fixed, which it often is in a home search.
2. The Same EMI, Five Tenures
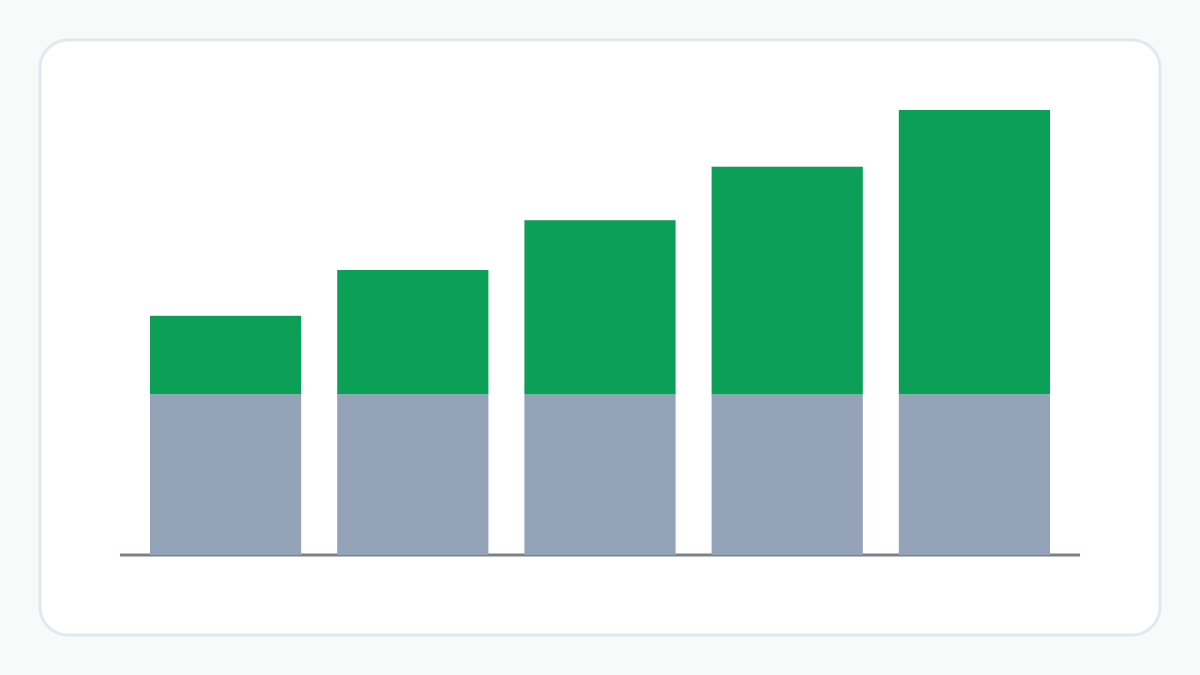
Take an EMI room of ₹30,000 a month at 8.5% a year. Over 10 years the loan that fits is ₹24,19,634, with total interest of ₹11,80,365.86. Over 15 years it is ₹30,46,490 and the interest ₹23,53,508.59. Over 20 years it is ₹34,56,925 and ₹37,43,074.59.
Over 25 years the loan is ₹37,25,657 and the interest ₹52,74,342.76. Over 30 years it is ₹39,01,609 and the interest ₹68,98,390.16.
From 10 to 30 years the loan that fits rises by about 61.25%, and the total interest is about 5.8 times as much. From 20 to 30 years the loan rises by about 12.86% and the interest by about 84.30%.
3. Why the Loan Grows Slowly
The EMI pays interest on the outstanding balance first, and what is left reduces the balance. Early in a long loan, most of each payment is interest, so adding years adds more months of interest than it adds principal that the same EMI can carry.
That is why the loan rises by about ₹6.3 lakh from 10 to 15 years but by only about ₹1.8 lakh from 25 to 30 years, while the extra years keep adding interest.
4. What This Does Not Tell You
The table does not say which tenure is right for anyone. A larger loan can matter for one buyer and the extra interest for another, and neither is a recommendation. It also assumes the rate stays the same for the whole tenure, and it leaves out fees, rate changes, tax benefits and part-payments.
It is not a lender's offer, and it does not use a lender's rules. It shows what the numbers do under the assumptions you enter.
Example: A ₹30,000 EMI Room at 8.5% a Year
10 years: ₹24,19,634 and ₹11,80,365.86 of interest. 15 years: ₹30,46,490 and ₹23,53,508.59. 20 years: ₹34,56,925 and ₹37,43,074.59. 25 years: ₹37,25,657 and ₹52,74,342.76. 30 years: ₹39,01,609 and ₹68,98,390.16.
The total repayments over those tenures are ₹35,99,999.86, ₹53,99,998.59, ₹71,99,999.59, ₹89,99,999.76 and ₹1,07,99,999.16.
The Bigger Picture
With a fixed EMI, a longer tenure buys a larger loan at a growing cost in interest. Seeing both numbers together, for your own income and rate, makes the trade-off visible without telling you how to weigh it.
Things to Consider
- Look at the loan and the total interest together, not one alone.
- Hold the EMI fixed when comparing tenures, as the table does.
- Remember that the rate is assumed to stay the same.
- Remember that fees, rate changes, tax benefits and part-payments are not in the figures.
Try the Home Loan Calculator
Enter your income, share and rate to see the same table of loans and interest across tenures for your own numbers.
Frequently Asked Questions
How is this different from the article on tenure and total interest?
That one keeps the loan the same and asks what a longer tenure does to the EMI and the interest. This one keeps the EMI the same and asks what a longer tenure does to the loan that fits.
Does this mean a longer tenure is better or worse?
No. It only shows that a longer tenure fits a larger loan and costs more interest. Which matters more depends on your own situation.
Why does each extra decade add less loan?
Because most of an early payment is interest. Extra years add more interest than they add principal the same EMI can carry.
How were the figures calculated?
With the Home Loan Calculator, using an income and share that give a ₹30,000 EMI room, 8.5% a year, and the tenures in the table. You can reproduce them by entering the same values.
Related Articles
Explore more practical guides from ToolZen Hub.