Why Reducing Home Loan Interest Matters
Even a small difference in the interest you pay can make a significant difference over a long home loan tenure. The total amount you repay depends not only on the loan amount and interest rate, but also on the tenure and your repayment strategy.
1. Compare Interest Rates Before Choosing a Loan
One of the first ways to reduce your borrowing cost is to compare available loan options. A lower interest rate can reduce both your monthly EMI and the total interest paid over the loan tenure.
When comparing loans, do not look at the interest rate alone. Consider the EMI, total interest, processing fees and other applicable charges.
2. Choose the Right Loan Tenure
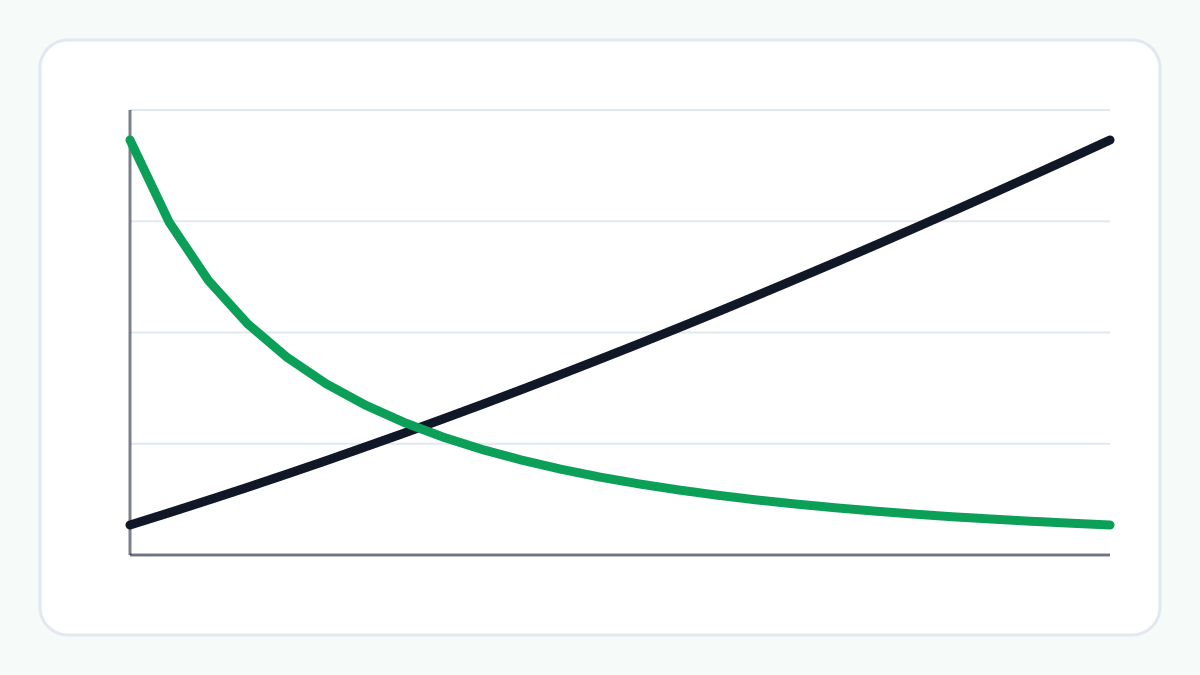
A longer loan tenure usually results in a lower monthly EMI, but it can also increase the total interest paid over the life of the loan.
A shorter tenure can increase your monthly EMI while reducing the overall interest cost. The right choice depends on how much you can comfortably afford each month.
3. Make Prepayments When Possible
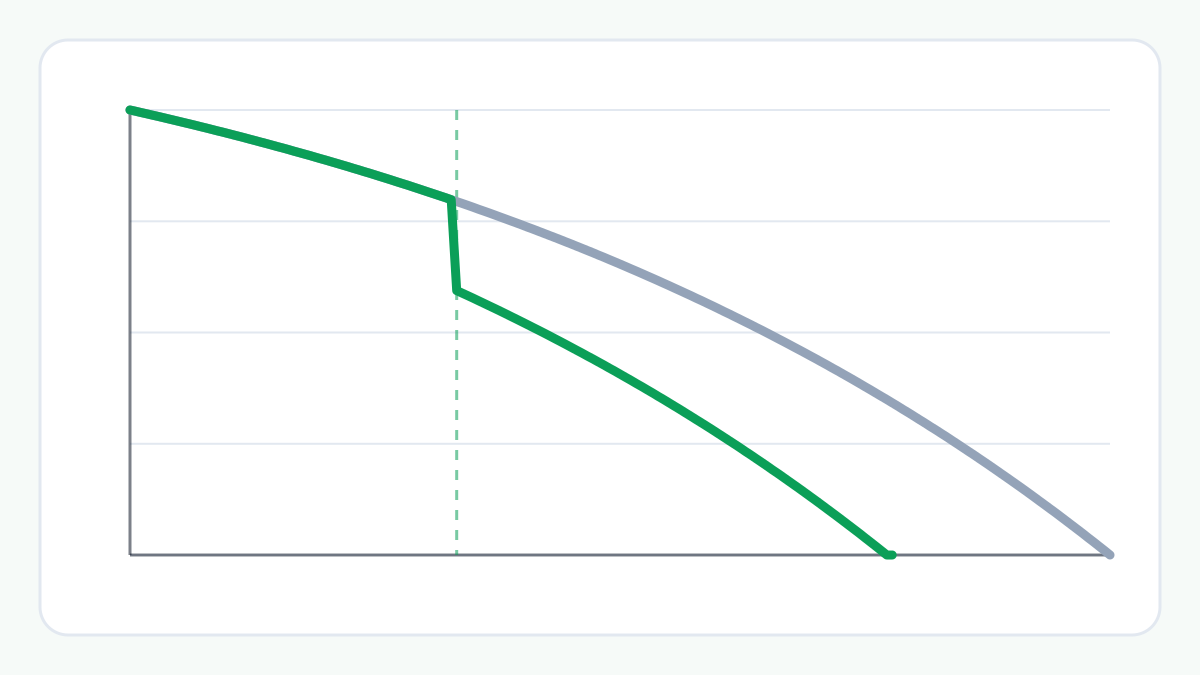
Making additional payments toward your home loan principal can reduce the outstanding balance. A lower principal means less interest may be charged over the remaining tenure.
Before making a prepayment, check the terms of your loan and understand any applicable charges or conditions.
4. Consider Increasing Your EMI
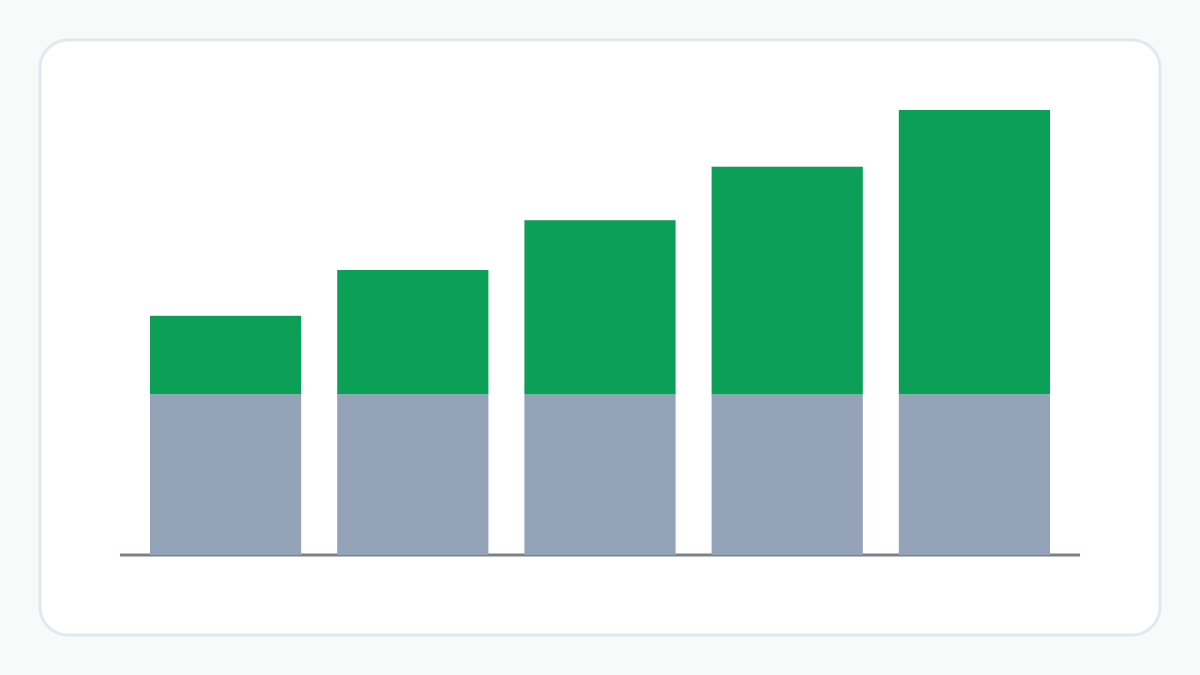
If your income increases over time, increasing your EMI may help you repay the loan sooner. Paying more toward the loan each month can reduce the outstanding principal faster and potentially lower the total interest cost.
5. Compare Your Loan When Rates Change
Interest rates can change during the life of a loan, especially for floating-rate loans. It can be useful to review your loan periodically and understand how changes in the interest rate affect your EMI and total repayment.
Example: How Tenure Can Affect Interest
Suppose you borrow ₹40 lakh for a home loan. Choosing a longer tenure may reduce the monthly EMI, but the loan may accumulate substantially more interest over time.
Comparing different loan amounts, interest rates and tenures before choosing a loan can help you understand the overall cost rather than focusing only on the monthly EMI.
The Bigger Picture
A well-planned home loan can make a long-term financial commitment easier to manage. Looking beyond the monthly EMI and understanding total interest, tenure and repayment flexibility can help you make more informed financial decisions.
Things to Consider
- Compare the total interest, not just the EMI.
- Choose a tenure that fits your monthly budget.
- Check processing fees and other loan charges.
- Understand the terms before making a prepayment.
- Review your loan when your financial situation or interest rate changes.
Compare Your Loan Options
Compare EMI, interest rate, total interest and total repayment to understand the overall cost of different loan options.
Frequently Asked Questions
Does a lower EMI always mean a cheaper loan?
No. A lower EMI may result from a longer loan tenure, which can increase the total interest paid.
Can prepayment reduce home loan interest?
Paying down the principal earlier can reduce the outstanding balance and may reduce the interest charged over the remaining tenure, subject to the terms of your loan.
Is a shorter home loan tenure better?
A shorter tenure can reduce total interest, but it usually results in a higher monthly EMI. The appropriate tenure depends on your financial capacity.
Related Articles
Explore more practical guides from ToolZen Hub.