1. What Is Loan Prepayment?
Loan prepayment is an additional payment made toward an outstanding loan before the originally scheduled repayment period ends.
Instead of paying only the regular EMI, a borrower makes an extra payment that is applied toward the outstanding loan balance according to the lender's terms.
2. How Does Loan Prepayment Work?
When you make a prepayment, the amount is generally used to reduce the outstanding principal of the loan. The exact process can vary depending on the lender and loan agreement.
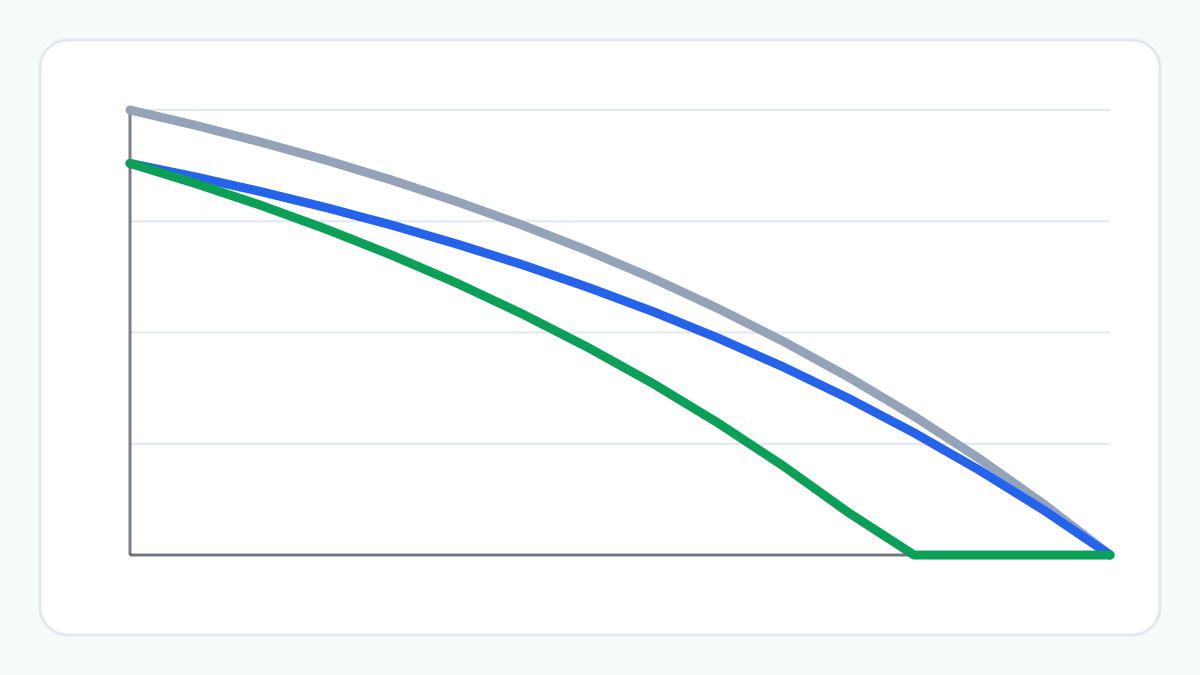
After the principal is reduced, the remaining repayment schedule may change. Depending on the lender's process and the borrower's preference, the effect may be reflected through a shorter tenure, a lower EMI or another repayment adjustment.
3. How Prepayment Can Affect Interest
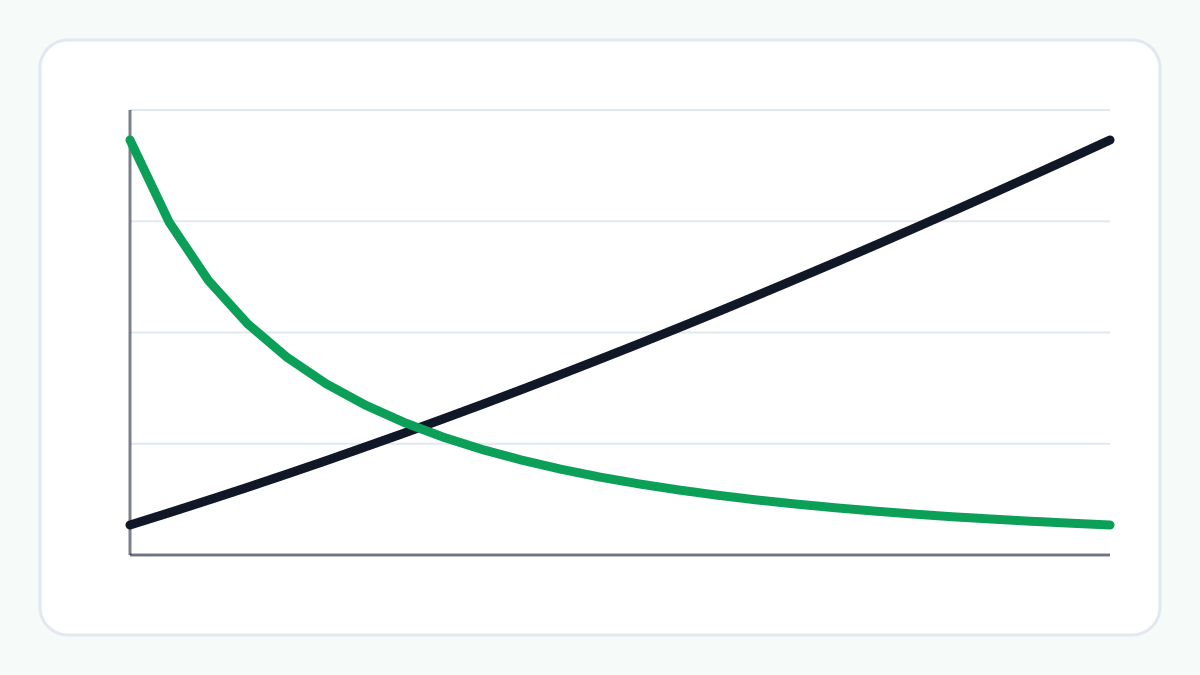
Loan interest is generally calculated based on the outstanding principal and the applicable interest rate. Reducing the principal earlier can therefore reduce the amount on which future interest is calculated.
The potential interest saving depends on factors such as the amount prepaid, the remaining tenure, the interest rate and the repayment structure.
4. Reduce Tenure or EMI After Prepayment
After a prepayment, some loan structures may allow the borrower to keep a similar EMI and reduce the remaining tenure. This can help repay the loan sooner.
Another possible approach is to reduce the EMI while keeping a similar remaining tenure. The option available depends on the lender and the terms of the loan.
Understanding both options can help you evaluate how a prepayment changes your monthly cash flow and overall repayment.
5. When May Prepayment Be Considered?
A borrower may consider prepayment when they have surplus funds available and want to reduce an outstanding loan balance.
Before using available savings for prepayment, it is important to consider emergency funds, other financial commitments and alternative uses for the money. The decision should also account for any applicable loan conditions or charges.
6. Things to Check Before Prepayment
Before making a prepayment, check the loan agreement and confirm whether any prepayment charges, minimum payment requirements or other conditions apply.
It can also be useful to compare the expected interest savings with the amount you plan to prepay. A loan calculator can help estimate how different prepayment amounts may affect the remaining repayment.
Example: Making an Additional Loan Payment
Suppose you have an outstanding loan and receive an additional amount of money that you could use toward the loan principal.
If the lender applies that payment to the outstanding principal, the remaining loan balance becomes lower. Future interest may then be calculated on a smaller outstanding balance, depending on the loan terms.
The actual impact depends on the amount prepaid, interest rate, remaining tenure and the lender's repayment rules.
The Bigger Picture
Loan prepayment can be one way to reduce an outstanding debt earlier, but it should be considered as part of your broader financial plan. Understanding the potential interest savings, repayment changes and applicable conditions can help you evaluate the impact of an additional payment.
Things to Consider
- Check the lender's prepayment rules and applicable charges.
- Understand how much of the payment will reduce the outstanding principal.
- Compare the potential interest savings with your other financial priorities.
- Maintain an appropriate emergency fund before using surplus cash for prepayment.
- Check whether the prepayment changes your EMI, tenure or repayment schedule.
Try the Loan Prepayment Calculator
Enter your loan balance, interest rate, remaining tenure and a prepayment amount to see how much interest and time it could save.
Frequently Asked Questions
What is loan prepayment?
Loan prepayment is an additional payment made toward an outstanding loan before the scheduled repayment period ends.
Can loan prepayment reduce interest?
It can. Reducing the outstanding principal earlier may reduce the amount on which future interest is calculated, depending on the loan terms.
Does prepayment reduce EMI?
Not necessarily. Depending on the lender and loan structure, a prepayment may reduce the remaining tenure, EMI or another part of the repayment schedule.
Should I always prepay my loan?
Not necessarily. Consider the potential interest savings, applicable charges, emergency savings and other financial priorities before making a prepayment.
What should I check before making a prepayment?
Check the loan agreement for prepayment charges, minimum payment requirements, eligibility conditions and how the lender adjusts the remaining repayment schedule.
Related Articles
Explore more practical guides from ToolZen Hub.