1. Why Timing Matters
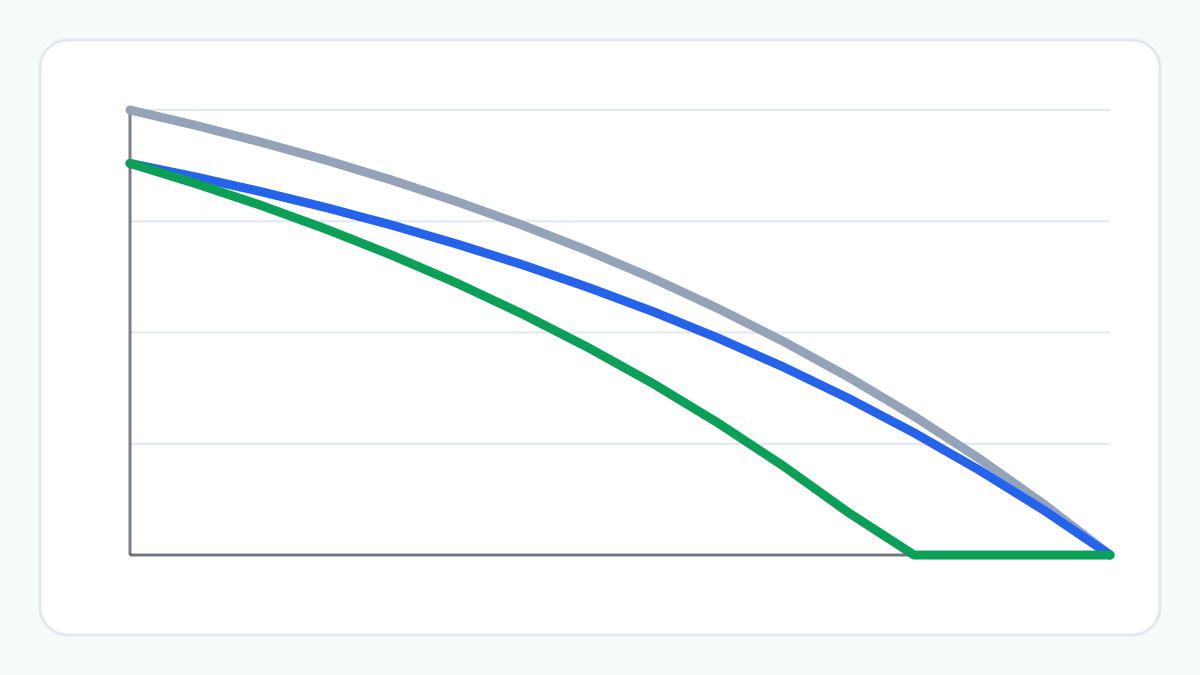
Interest is charged on the balance you still owe, and that balance is highest at the start of a loan. So a large share of each early EMI goes to interest and only a small share reduces the principal.
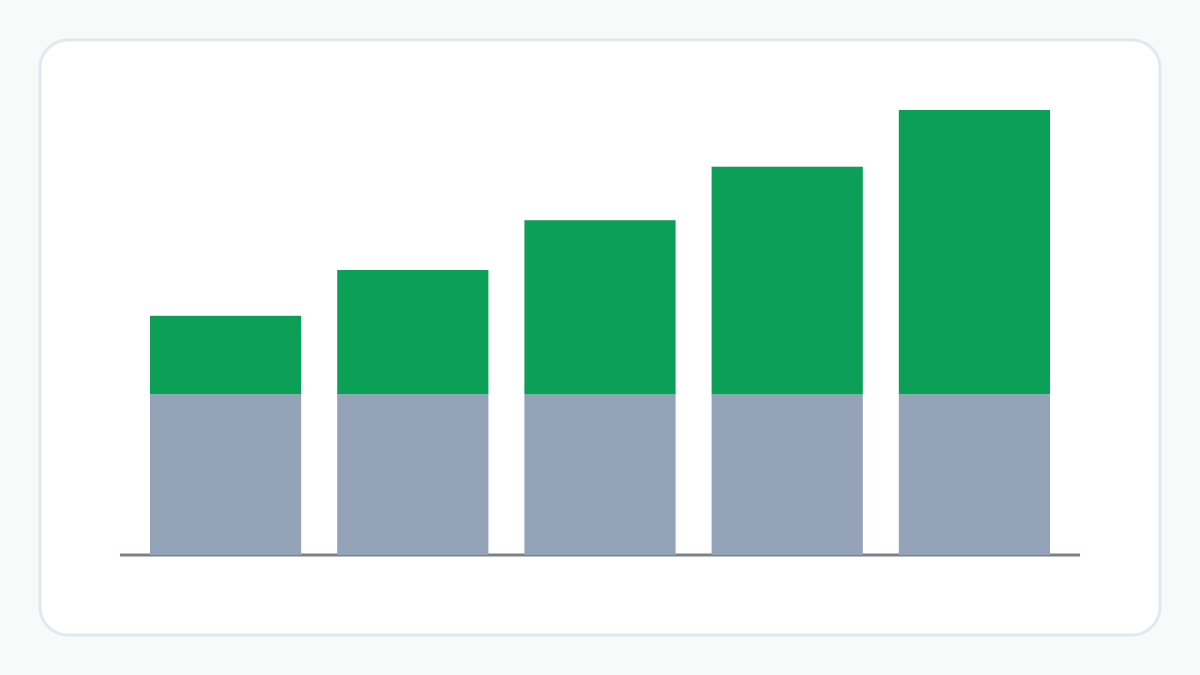
On the loan in the example below, about 71.9% of the first EMI (₹17,708 of ₹24,618) is interest. By the 61st EMI it is about 57.1% (₹14,065), and by the 121st about 34.5% (₹8,500).
A rupee prepaid early removes principal that would otherwise have been charged interest for many years. A rupee prepaid late has far less time left to save anything.
2. What the Pattern Shows
Measured against the amount prepaid, the saving falls from about ₹2.12 of interest for every ₹1 prepaid when the payment is made right away, to about ₹1.68 after 2 years, ₹1.13 after 5 years and ₹0.44 after 10 years.
The time saved shrinks in the same way, from 3 years 1 month to 1 year 5 months. The change is gradual rather than sudden: each extra year of waiting reduces the benefit a little more.
3. What This Does Not Tell You
These figures describe what a prepayment does at different times. They do not say when, or whether, you should prepay. Making an early prepayment needs money to be available, and that money may have other uses.
Emergency savings, other debts, your lender's prepayment rules and any charges all matter too. This article gives information, not advice.
4. Try Your Own Timing
In the Loan Prepayment Calculator, the Make the Prepayment After field sets when the prepayment happens. Entering 0 means right away, before your next EMI. Entering 24 means after 24 more EMIs have been paid.
Enter your own balance, interest rate, remaining tenure and prepayment, then change that one field to see how much the timing alone changes the result.
Example: ₹3,00,000 Prepaid at Four Different Times
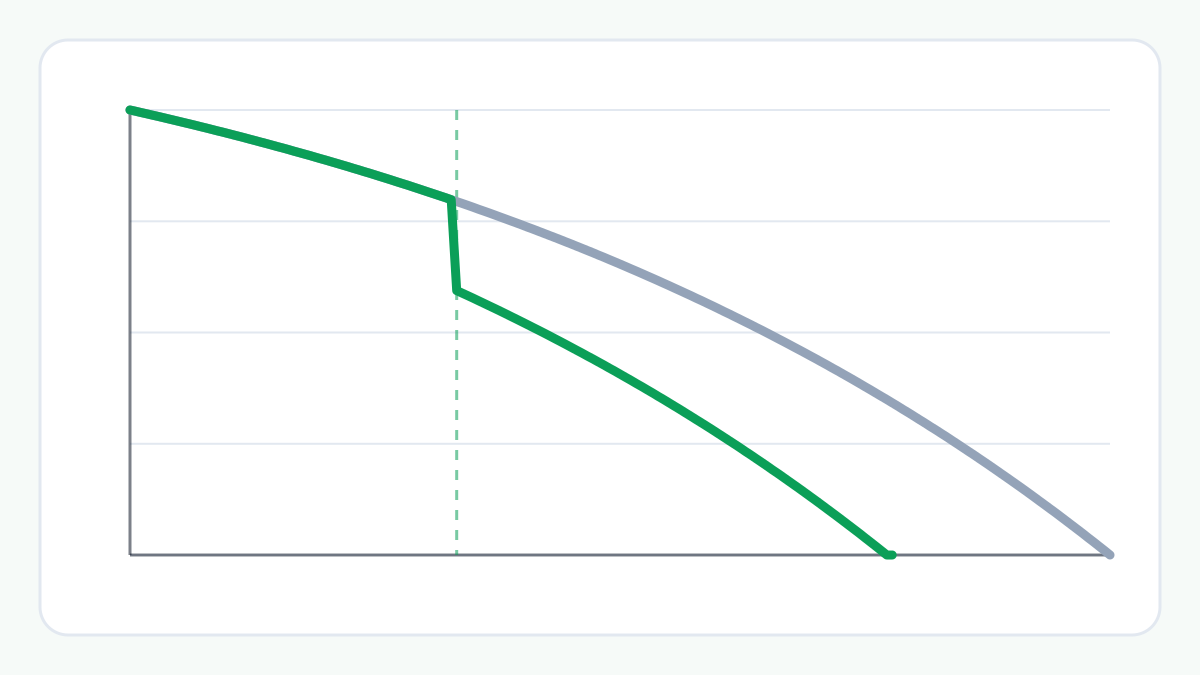
Suppose you owe ₹25,00,000 at an interest rate of 8.5% a year, with 15 years (180 monthly payments) left. The EMI is about ₹24,618 and, without a prepayment, the interest over the remaining 15 years is about ₹19,31,328. In each case below, the EMI is kept the same and no charges are included.
Prepaid right away: the loan ends after 11 years 11 months, which is 3 years 1 month sooner, and the interest saved is about ₹6,35,199.
Prepaid after 2 years (24 EMIs): the loan ends after 12 years 4 months, which is 2 years 8 months sooner, and the interest saved is about ₹5,04,951.
Prepaid after 5 years (60 EMIs): the loan ends after 12 years 11 months, which is 2 years 1 month sooner, and the interest saved is about ₹3,39,823.
Prepaid after 10 years (120 EMIs): the loan ends after 13 years 7 months, which is 1 year 5 months sooner, and the interest saved is about ₹1,31,906.
The Bigger Picture
Because loan interest is charged on a balance that shrinks over time, the same payment does more work the earlier it is made. Seeing that effect with your own numbers helps you judge how much a prepayment, and its timing, would change your loan.
Things to Consider
- Timing changes the size of the saving, but it does not tell you whether prepaying is right for you.
- Check your lender's prepayment rules, charges and how it applies a payment.
- Keep an appropriate emergency fund before using surplus money for a prepayment.
- Compare the interest saved with your other financial priorities.
- Remember that the figures are estimates from a standard monthly model.
Try the Loan Prepayment Calculator
Use the Make the Prepayment After field to see how the timing of your own prepayment changes the result.
Frequently Asked Questions
Does prepaying earlier always save more interest?
For the same amount on the same loan, under the standard model used here, an earlier prepayment saves at least as much interest as a later one, because it reduces the balance for longer. Real results depend on your lender's terms.
Why is so much of an early EMI interest?
Interest is charged on the balance you owe, which is highest at the start. A larger share of the early EMIs therefore goes to interest and a smaller share to principal.
Is a late prepayment pointless?
No. It still reduces the balance, and the interest charged from then on, but there is less time left for the saving to build up, so the amount is smaller. Whether it makes sense depends on your circumstances.
How were the figures calculated?
With the Loan Prepayment Calculator, using a standard monthly model with the EMI kept the same and no charges. You can reproduce them by entering the same values.
Related Articles
Explore more practical guides from ToolZen Hub.