1. Working Backwards
A projection normally goes forwards: a SIP, a return and a period give an estimated value. A target reverses it: given the value you want, what starting SIP is needed under the same return and period?
Because the estimated value grows in proportion to the SIP, the answer is simple to work out. The starting SIP needed is the target divided by the value that a SIP of ₹1 would reach under the same assumptions.
2. The Answer Depends on the Assumption
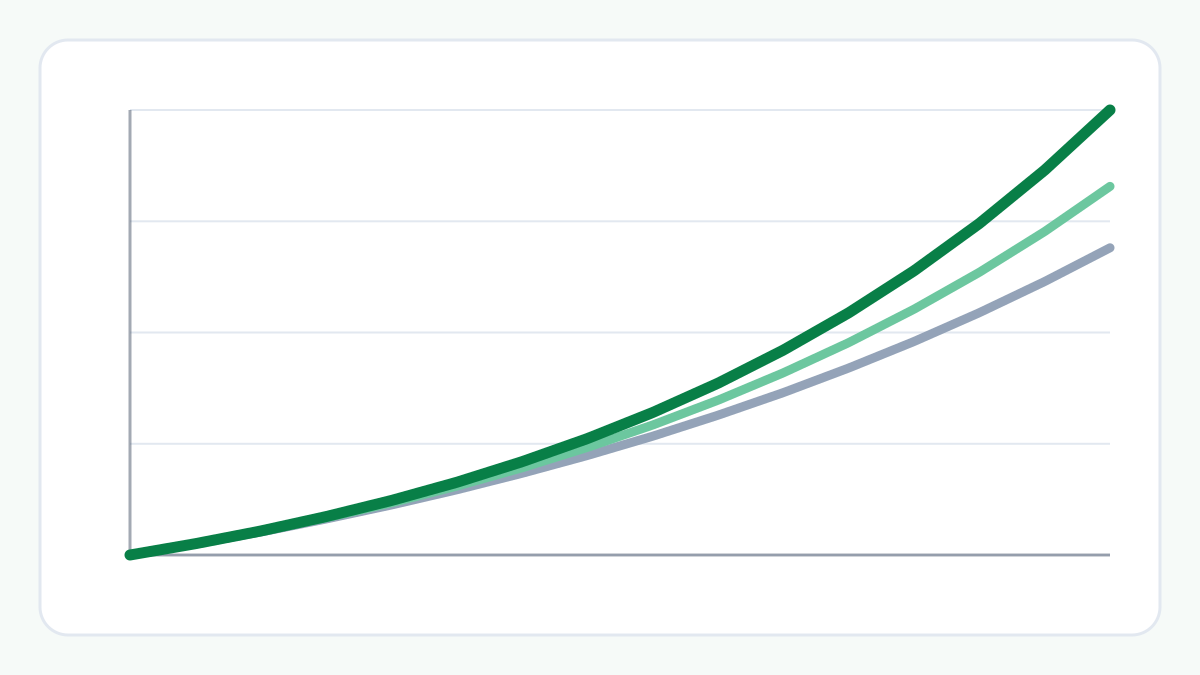
For a target of ₹1,00,00,000 after 15 years with a fixed SIP, the starting SIP needed is about ₹28,708 a month at an assumed return of 8%, about ₹23,928 at 10% and about ₹19,819 at 12%.
So a four-point difference in the return you assume changes the monthly amount by about ₹8,900, close to half of the lowest figure. That is why the answer should be read as a range of scenarios, not as the amount a goal requires.
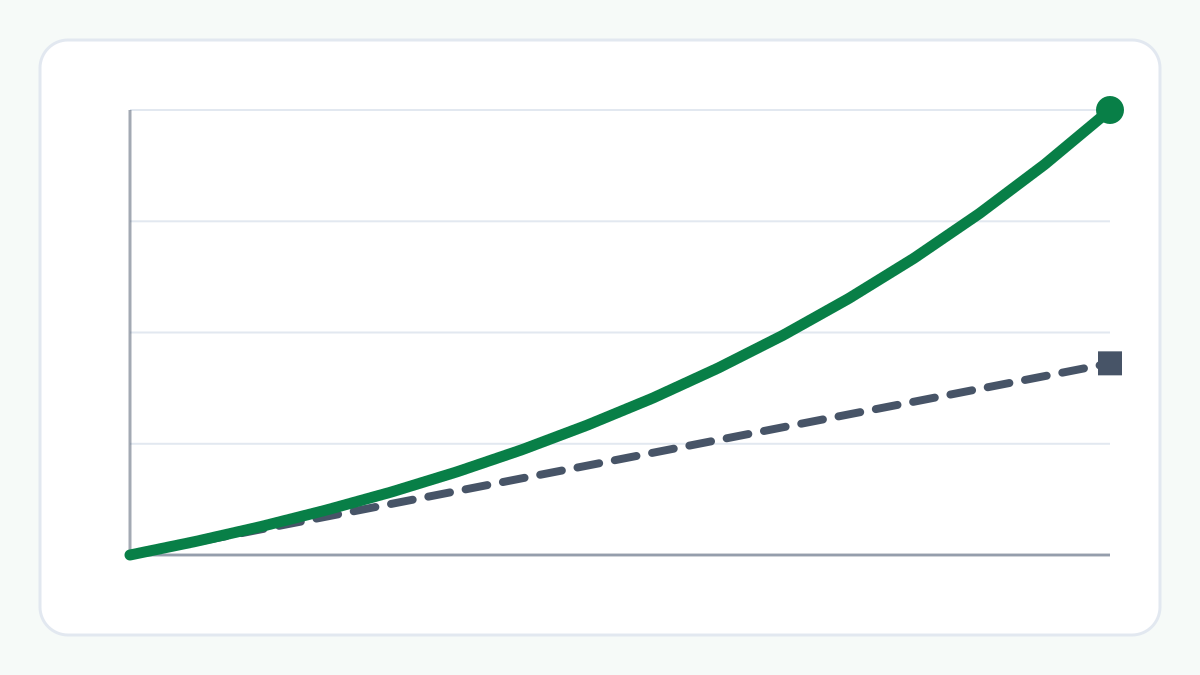
Against the target, a ₹10,000 SIP at an assumed 10% for 15 years projects to about ₹41,79,243. That may fall short of ₹1,00,00,000 by about ₹58,20,757.
3. How a Step-Up Changes It
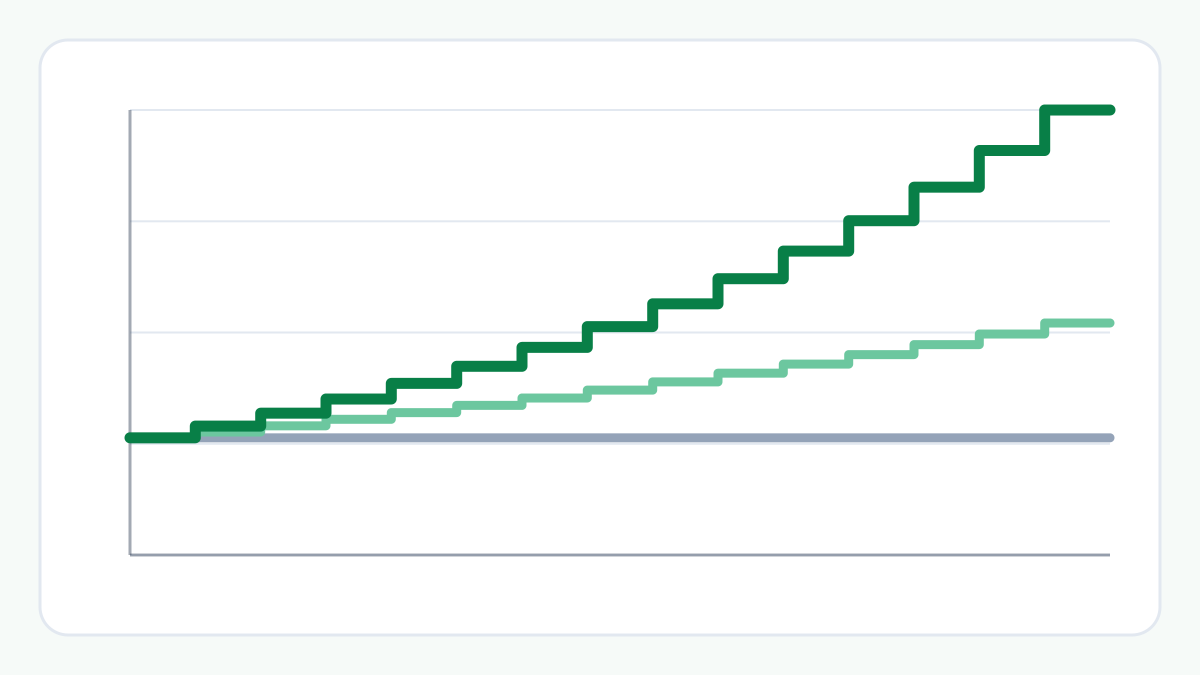
If the monthly amount rises by 10% every year, the starting SIP needed for the same target at an assumed 10% falls to about ₹13,445 a month. The target is reached by larger instalments later, not by a smaller total.
A ₹10,000 SIP with a 10% yearly step-up projects to about ₹74,37,840 over 15 years, which may fall short of ₹1,00,00,000 by about ₹25,62,160.
4. What This Does Not Tell You
A required SIP is only as reliable as the return behind it. Returns are not guaranteed, can be lower than assumed and can be negative, so reaching a target is never certain, and investments are subject to market risk.
The estimate leaves out taxes, fund charges, exit loads and inflation. In particular, ₹1 crore in 15 years will buy less than ₹1 crore does today. This article gives information, not advice.
Example: A ₹1,00,00,000 Target in 15 Years
With each SIP invested at the start of the month and the annual return divided by 12 each month, a fixed SIP would need to start at about ₹28,708 a month at an assumed 8%, about ₹23,928 at 10% and about ₹19,819 at 12%.
With a 10% yearly step-up at an assumed 10%, the starting SIP needed is about ₹13,445 a month.
If a plan is already larger than the amount needed, the calculator shows an estimated surplus instead. For example, ₹50,000 a month at an assumed 12% for 20 years projects to about ₹4,99,57,396, and the starting SIP needed for ₹1,00,00,000 under the same assumptions is about ₹10,009.
The Bigger Picture
Working backwards from a goal turns a projection into a planning question, but the answer is still only as firm as the return you assumed. Looking at it at more than one assumption, and with and without a step-up, shows the range of monthly amounts a goal might involve.
Things to Consider
- Treat the amount needed as a scenario, not a requirement.
- Try more than one assumed return.
- Remember that a target in future years is worth less than it looks, because of inflation.
- Check that the amount, and any step-up, fits your own circumstances.
- Remember that investments are subject to market risk.
Try the SIP Calculator
Enter a target amount to see whether your plan may reach it, by how much, and the starting monthly SIP it would need.
Frequently Asked Questions
Will this SIP definitely reach my target?
No. The calculator shows whether the projection may reach the target under the return you assumed. Real returns can be lower, and can be negative.
Why does the starting SIP change so much with the return?
Over a long period, a higher assumed return adds more growth, so a smaller SIP can reach the same target. The change compounds.
Does the required SIP include inflation?
No. It is a figure in future rupees. Inflation would make the same amount worth less by then.
How were the figures calculated?
With the SIP Calculator, using a standard monthly model: each SIP is invested at the start of the month and the annual return is divided by 12. You can reproduce them by entering the same values.
Related Articles
Explore more practical guides from ToolZen Hub.